
Dollarwise: Budget & Tracking
- Rating
- 3.3
- Downloads
- 100.00K
- Content Rating
- Everyone
Dollarwise: Budget & Tracking - Screenshots
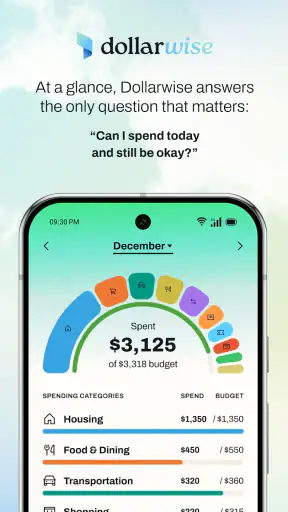
Pros
- Quickly logs income and expenses for everyday spending control.
- Clear category breakdowns make it easier to spot costly habits.
- Budget limits help users stay focused on monthly spending goals.
- Useful tracking history supports better financial decisions over time.
- Simple interface is approachable for users new to budgeting apps.
Cons
- Some advanced tools may require a paid subscription.
- Manual entry can become tedious for users with many transactions.
- Accuracy depends on consistently categorizing every expense.
- Limited investment and debt-management features may disappoint advanced users.
- Financial data privacy policies should be reviewed before adding sensitive details.
Dollarwise: Budget & Tracking - Description
- App Name
- Dollarwise: Budget & Tracking
- Package Name
- com.hammer.simplebudget
- Developer
- HammerMedia
- Category
- Finance
- Last Updated
- Jan 9, 2025
- Version
- 6.4.0
I approached Dollarwise: Budget & Tracking as a decision rather than a quick download. A finance app can look useful in a screenshot and still become annoying after a week, especially if recording spending feels like another chore. My experience with this one is that its appeal depends less on flashy presentation and more on whether you want a simple place to rethink how money moves through your day.
Developed by HammerMedia, Dollarwise is a free finance app for everyone, with optional in-app purchases ranging from $14.99 to $499.99 per item. It has reached over 100 thousand installs, while its average sits at 3.3 from around 2.2 thousand ratings and roughly 1.2 thousand written reviews. Those figures suggest a product with real interest but also a mixed experience, so I would not recommend installing it without first deciding what job you expect it to do.
The central question is straightforward: do you need a lightweight budgeting companion that encourages awareness, or do you need a complete financial command center? Dollarwise makes more sense for the first situation. If your priority is to notice patterns, create a more deliberate spending routine, and check whether your daily choices match your plans, it is worth considering. If you expect deep account connectivity, sophisticated forecasting, or highly detailed financial reporting, a different type of tool may suit you better.
How I Would Decide Whether Dollarwise Fits
Start with the habit you actually want to build
Before comparing finance apps, I would identify the behavior causing the problem. Someone who regularly forgets small purchases needs a quick tracking routine. Someone who has several accounts, investments, recurring bills, and shared household expenses needs structure at a much deeper level. These are not the same need, even though both people may search for a “budget app.”
Dollarwise is most appealing when the first step is awareness. I found the idea of giving every purchase a deliberate place more useful than chasing perfect financial records. That distinction matters because the value of a tracker often comes from returning to it consistently, not from filling it with every possible detail on the first day.
I would also consider how much manual attention I am willing to give. A budget tool that asks me to participate can make spending more visible, but it also depends on my discipline. If I know I will ignore entries after a busy week, an automated alternative may be more practical, even if it offers less intentional reflection.
Look beyond the word “free”
The app is free to download, but the presence of optional purchases means I would inspect the upgrade screen carefully before committing to a long-term workflow. A free starting point is useful for testing the basic experience, yet a budgeting routine becomes inconvenient if the functions I rely on later turn out to sit behind a purchase.
The listed purchase range is unusually broad, from $14.99 to $499.99 per item. I would treat that as a reason to read each offer rather than assume every user sees the same value. A high-priced option may be irrelevant to someone who only wants basic tracking, while a person seeking a more complete experience should compare the cost with established alternatives before entering a lot of personal financial information or building a routine around the app.
My practical advice is to begin with a short trial period using only the information needed to test the workflow. Record ordinary purchases, review the results, and decide whether the process feels natural. Do not start by rebuilding your entire financial life inside any app. The best budgeting system is the one you can maintain when you are tired, busy, or distracted.
Think about privacy and control in everyday terms
Finance apps invite a different level of caution from entertainment apps. Even when I am only tracking spending manually, the entries can reveal routines, priorities, and sensitive personal details. I would therefore avoid entering information that is not necessary for the particular budgeting experiment I am running, especially during the first few days.
This is also where manual tracking can be both a strength and a weakness. It gives me control over what I record, but it places responsibility on me to keep the information accurate. If I enter a purchase late, forget a cash expense, or assign something inconsistently, the resulting picture can be misleading. Dollarwise cannot correct a habit I do not maintain.
Where the app feels most useful
The strongest use case I see is a person who wants a clearer relationship with everyday spending without immediately adopting a complicated financial system. Imagine arriving home after several small purchases: coffee, transport, a snack, and an unexpected item from a shop. None of those expenses feels dramatic alone, but together they explain why the week went off course. A tracker such as this can turn that vague feeling into something I can examine and act on.
A second useful scenario is preparing for a short-term goal. I might decide to reduce unnecessary spending for the next few weeks, use Dollarwise to record the choices that matter, and review where the plan is holding or slipping. The benefit is not a magical prediction. The benefit is creating a pause between impulse and habit.
A third scenario is returning to budgeting after abandoning it. Many people do not need another complex template; they need a low-friction restart. In that situation, I would use a small number of categories, review them at a fixed time, and resist the temptation to design an elaborate system immediately. Starting modestly makes it easier to tell whether the app itself is helping.
What Dollarwise Does Well, and Where Another Approach May Be Better
Its best advantage is intentional attention
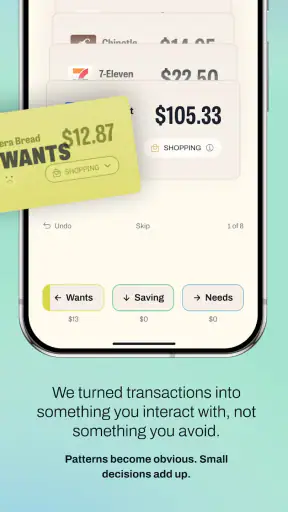
What separates Dollarwise from a basic notes file is the expectation that spending should be observed as part of a budgeting process rather than stored as an unstructured list. That framing can be surprisingly valuable. When I label a purchase and later look back at it, I am more likely to notice a repeated choice than when the same amount disappears into a bank statement.
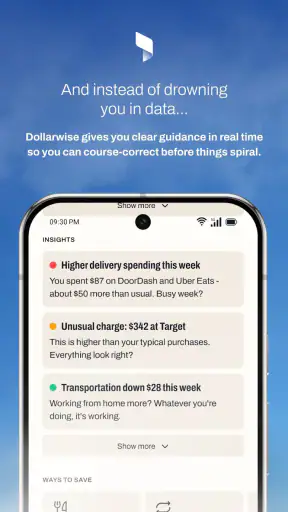
I also like the possibility of using it as a review tool rather than checking it constantly. A short evening check can be enough to keep the record current. A longer weekly review can then focus on decisions: which expenses were planned, which were avoidable, and which were simply necessary. This two-stage workflow is more sustainable than turning every purchase into a major financial analysis.
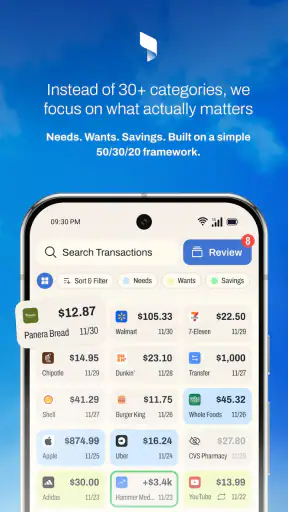
Another non-obvious strength is that a deliberately limited setup can make the app more useful. I would begin with broad categories that reflect actual decisions, such as food away from home, transport, household needs, and optional purchases. If categories become too specific, recording stops being a budgeting aid and becomes administrative work. Dollarwise works best when the structure helps me choose, not when it demands perfect bookkeeping.
Do not confuse tracking with financial automation
There is an important trade-off here. A tracking app can make me more aware, but awareness is not the same as automatic account reconciliation. If I want transactions to appear without my involvement, I would look toward a bank-connected money manager or another automation-focused category. That type of service may save time, although it can also introduce more setup, account access considerations, and clutter than I want.
For someone managing a household with another person, the decision becomes even more specific. A shared spreadsheet or collaborative budgeting service may be better if both people need to enter expenses, see changes immediately, or divide responsibilities. Dollarwise may still help one person understand their own spending, but I would not choose it solely on the assumption that it will replace a shared household system.
People who need tax preparation, investment monitoring, debt amortization, or detailed cash-flow forecasting should also compare other categories. A general tracker can support better habits, but it should not be treated as professional financial advice or as a substitute for specialized software. The more complex the financial situation, the more important it is to choose a tool around the required workflow rather than the app’s attractive simplicity.
How it compares with familiar alternatives
The usual alternative is a spreadsheet. A spreadsheet offers almost unlimited flexibility and can be adapted to unusual income patterns, shared budgets, or custom formulas. Its weakness is that the user has to design and maintain everything. Dollarwise is the more approachable choice if I want a ready-made budgeting context and do not want to spend an evening building columns, categories, and summaries.
Another alternative is a notes app. Notes are fast and private in the sense that I control the content, but they make review difficult. A month of unstructured entries can tell me what I bought without helping me see a pattern. Dollarwise is preferable when I want the record to support decisions rather than merely preserve information.
Banking apps are convenient because they already contain transaction history. They can be better for checking balances and confirming charges, but they may not encourage the same deliberate pause before spending. I see Dollarwise as more useful for personal reflection, while a banking app remains the authority for account balances and completed transactions.
Finally, there are full-featured budgeting platforms. They may be stronger for people who want automation, multiple accounts, shared planning, or extensive reports. The cost is often complexity: more setup, more decisions, and more information to maintain. Dollarwise wins when I want to begin with a focused habit and avoid turning budgeting into a second job.
Small workflows that make the experience more reliable
My first recommendation is to create a “review later” habit for uncertain purchases instead of spending too long deciding on a category. Make a quick, consistent entry, then resolve unusual items during the weekly review. This keeps daily tracking fast while preserving enough accuracy for useful conclusions.
Second, I would separate necessary spending from spending that reflects a choice. That distinction is more actionable than simply ranking categories by size. A large essential bill may not be easy to change, while several small optional purchases may reveal the behavior that is actually disrupting the budget.
Third, I would use the app to test one change at a time. For example, I might focus on reducing unplanned food purchases for a week rather than attempting to control every category simultaneously. This creates a clearer before-and-after comparison and prevents the common mistake of making a budget so strict that it collapses immediately.
Fourth, I would keep a backup habit outside the app for important financial information. That does not mean duplicating every entry forever. It means retaining access to official statements and receipts so that the tracker remains a planning aid rather than the only record I trust.
The cost of changing systems later
Switching budgeting tools is easier when I treat the first setup as an experiment. I would avoid entering years of history until I know that Dollarwise fits my routine. Start with current spending, learn how reviews feel, and decide whether the categories help. This reduces the emotional and practical cost of leaving if another tool turns out to be a better match.
The main switching cost is not just data entry. It is habit disruption. If I have learned to record purchases in one place, moving to a spreadsheet or an automated platform means learning a new rhythm and possibly redefining categories. That is why I would judge Dollarwise by consistency over several ordinary days rather than by the first impression after installation.
Its current version is 6.4.0, and it supports Android 7.0 or later, which makes it accessible to people using older Android devices. That broad compatibility is helpful if I do not want budgeting to depend on buying a newer phone. Still, compatibility alone does not determine whether the app belongs in my long-term routine; the practical test is whether recording and reviewing remain clear enough to continue.
Who should use it and who should skip it
I would recommend Dollarwise to a beginner who wants to become more conscious of spending, someone restarting after abandoning a budget, or a user who prefers a focused tracker over a large financial dashboard. It is also a reasonable option for a person who wants to experiment before paying for a more advanced service.
I would be more cautious for anyone who needs automatic transaction imports, detailed joint budgeting, investment oversight, or formal financial reporting. In those cases, an alternative designed around connected accounts or specialized analysis may save time and reduce manual errors. I would also skip it if I already have a reliable system that I use consistently; changing tools merely because a new one looks appealing can create more friction than improvement.
My recommendation after weighing the trade-offs
Dollarwise: Budget & Tracking is best understood as a habit-building finance app, not an all-purpose replacement for every money tool. I appreciate its potential to make ordinary spending more visible and to give a beginner a manageable starting point. The free entry point makes testing straightforward, while the optional purchases mean I would examine the upgrade terms carefully before treating it as a permanent solution.
My recommendation is conditional but positive: try it if your main goal is to track daily choices and create a regular review habit. Keep the setup small, use broad categories, and evaluate whether the routine survives a busy week. If you need automation, shared finances, or advanced planning, compare it with a spreadsheet, a bank-centered tool, or a full budgeting platform instead.
In the end, the app’s real test is not whether it can display a tidy budget. It is whether it helps me make one better decision before the next purchase. For that focused purpose, Dollarwise: Budget & Tracking can be a useful companion. I would simply choose it with clear expectations: its value comes from the attention I bring to the process, and no finance app can replace that part.
FAQ
What is Dollarwise: Budget & Tracking used for?
Dollarwise: Budget & Tracking is designed to help you organize personal finances in one place. You can record income and expenses, categorize transactions, monitor spending habits, and compare your progress with a budget. It is useful for people who want a clearer overview of where their money goes, although it works best when transactions are entered consistently and accurately.
Is Dollarwise: Budget & Tracking suitable for beginners?
Yes, the app is generally suitable for beginners because its main purpose is straightforward: create a budget, track spending, and review financial activity. New users may need a little time to set up categories, income sources, and recurring expenses, but the process is manageable. Starting with a simple monthly budget can make the app easier to understand before adding more detailed tracking.
Does Dollarwise: Budget & Tracking connect directly to bank accounts?
Users should check the current app description and settings before downloading because account-connection features can vary by platform, region, subscription level, or app version. If automatic bank synchronization is unavailable, expenses and income may need to be entered manually. Manual tracking provides more control and privacy, but it requires regular updates to keep the budget accurate.
Is Dollarwise: Budget & Tracking free to use?
Dollarwise: Budget & Tracking may offer a free version, while certain advanced tools, expanded limits, or premium features could require an in-app purchase or subscription. Pricing and included features can change over time, so it is important to review the store listing and subscription terms before confirming payment. Also check whether a trial automatically converts into a paid plan.
Is my financial information safe in Dollarwise: Budget & Tracking?
Before entering sensitive financial details, review Dollarwise’s privacy policy, permissions, and data-handling information in the Google Play Store or Apple App Store. Avoid sharing banking passwords unless a trusted, clearly documented connection method is provided. Using a device lock, keeping the app updated, and entering only the information necessary for budgeting can further reduce privacy and security risks.


